Sunday, January 18, 2015

The Significance of Copper's Current Price Moves

As if the plunging prices of oil weren't enough to worry about, pundits are now citing a "crash" in copper prices as further confirmation that the health of the global economy is deteriorating rapidly.  I've heard some question whether copper is signalling a global recession, or if it's signalling significant weakness in the US and China at the very least.  Well, before we start forecasting impending doom, let's take a step back and look at this "crash" from a broader perspective.  Here's the weekly chart of copper prices from 1/3/2000 to the present.

$COPPER EOD Price
As you can see from the chart, Copper has a tendency to follow global economic health.  Whether or not we can call it a leading indicator is somewhat doubtful, though, and in my view it would be a stretch of the imagination.  The two shaded green areas on that chart show the extreme market crashes that followed the September 11 attacks in 2001 and the financial crisis in 2008. 

Nobody will argue that any market indicator could have foreseen the market crash following a major terrorist attack, so there were no leading indicators that would have foreshadowed the post 9/11 crash.  Yet, as you can see from this chart, Copper started heading down following a peak over a year earlier.  Conclusion: there was no correlation between the two.

Look at the 2008 scenerio.  Again, Copper was trading in a very gradual incline until the financial crisis hit, and it then followed global markets down, just like every other commodity.  The key is, it followed, but it didn't lead.  Benefiting from a plunging dollar and a surge in economic growth in China, Copper surged from mid-2008 until the Commodity Bubble burst in 2011. 

The 2011 burst of that bubble was inevitable, since it was not possible for China to continue the level of growth it had sustained for the prior three years.  As China slowed, so did the demand for copper, and the prices gradually declined.  You can see from the chart, in fact, that the price managed to find some support around the 61.8% Fibonacci Retracement line, until it finally penetrated that line for good in November, 2014.

In the past two months, we've seen a significant drop in price back to the 50% Fibonacci line, but before we panic, let's stop and thing about what drives the price of copper.  There are three factors:

1.  Demand, primarily in China.  Well, that demand appears to be holding steady.  It's not growing, but neither is it dropping at any significant rate.  In fact, some of the early guidance we're hearing out of companies with exposure to China seem to indicate modest growth there for 2015, so I don't think weakening demand is driving the price down.

2.  Supply.  Well, it's definitely possible that there's an increase in supply.  There was speculation last week coming out of Morgan Stanley's commodities analysts that a drop in oil prices would encourage mining companies to increase their production of commodities such as copper.  It's possible, but I doubt that's what we're seeing in the current price drop.

3.  Strength of the US Dollar.  Here, folks, we have the winner.  The price of commodities, including copper, carries an inverse relationship to the value of the dollar.  As the dollar increases, commodities prices fall. What we've had in the last few months is a very sharp increase in the value of the US Dollar, culminating with Friday's 10-year high against the Euro.  This factor alone fully accounts for the sharp drop in copper prices last week.

Is the global economy weakening?  I'd certainly say Europe's is weakening, but China appears to be holding steady, as is the economy in the US.  Growth is weaker than I'd like it to be, but there's nothing out there indicating an imminent recession.  So when we look at the plunging prices of commodities in general and copper in particular, let's not forget that it's more than a supply and demand equation.  Factor in the value of the dollar and we have a perfectly good explanation for the behavior without resorting to a doom and gloom economic forecast.


Saturday, January 17, 2015

Schlumberger Hints at Global Growth, Oil Pressures in 2015

Schlumberger Limited's (NYSE: SLB) earnings conference call yesterday provided some interesting insight into the global growth potential for 2015 as well as a detailed view of the changing dynamics we are witnessing within the oil industry.  For those not familiar with this global company, Schlumberger provides technology, project management, and information solutions to global oil and gas exploration and production (E&P) corporations.  Their clients operate in over 80 countries, giving them a unique view into the health of the economy both domestic and global.

Despite currency weakening both in Russia and Europe, Schlumberger foresees healthy growth in the global economy, surpassing the growth seen in 2014.  They see demand for oil increasing by about one million barrels per day by 2016.  This is matched by the one million barrels per day increase being supplied by the global oil market.

The dramatic drop in prices that we've seen is primarily being driven by a significant increase in supply coming out of North America and Saudi Arabia.  Globally, Saudi Arabia has shifted their strategy from one in which they sought to protect the price of oil via a manipulation of the supply to one in which they seek to protect their market share via an increase in supply regardless of the impact on price.  It's a fundamental shift in philosophy, and it's one to which the rest of the world has yet to fully react.

The impact of this strategy shift and resulting price drop is already being felt.  Exploration and Production (E&P) are down significantly, and are projected to drop by 25% to 30% in the US next year, coupled with a 10% to 15% drop globally.  Already, some 400 oil rigs have been taken offline, due to profitability issues relative to the new oil price point.

Hydraulic Fracturing technologies in the US and Canada have made a significant contribution to the oversupply of oil coming out of North America.  In the realm of cost, however, this technology is one of the highest - much higher than the cost of traditional oil wells that have both a lower start-up cost and a longer life span per site.  (Production from fraked sites declines 45% per year as compared to 5% per year from traditional wells.)  The Arabian oil companies have the lowest production costs and can therefore ride out this wave of low prices to the detriment of all competitors. The break-even point on some Arabian wells is a mere $10 per barrel.  Average break-even in the Gulf-States is $27 per barrel.  US Shale, on the other hand, has a break-even point optimistically at $50 per barrel, and some of the newer sites are even in the $80 per barrel range.  Clearly, the Saudis have the price advantage and can win the market share game simply by holding prices below $50 per barrel indefinitely. 

The impact is being felt beyond North America.  In the North Sea, both UK and Norwegian oil-rig counts are lower today and are projected to be even lower in 2015.  Those wells are simply not profitable at the current price point.  Not only are rigs being taken offline worldwide, but applications for new wells are down over 50%, and Cap-Ex spend projections for next year are being lowered tremendously.  Financing for new exploration and drilling is expected to be difficult to obtain, again due to profitability.  That will be exacerbated by rising interest rates should that happen.

What this means in the medium to long term is two-fold.  At the moment, Saudi Arabia is antagonizing one of the largest industries in their largest global political ally.  Expect the petroleum lobby to begin to apply political pressure in the White House and in Congress, if that hasn't already started.  This will change the politics between US and Saudi relations, and anytime you have a changing political dynamic in the Middle East, events can become very volatile very fast.

The second outcome will be tightening of supply, which will result in a rise in oil prices.  Nobody is willing to predict when that will occur, but it's definitely on the horizon for sometime in 2015.  Even if it's not an overt action taken by the industry, it will be a de facto result as the more expensive drilling operations either go offline until prices rise, or they go bankrupt in the face of insurmountable losses.  A look at the overall break-even points for the various producers will provide an excellent investment opportunity since they are the ones most able to survive this downturn in price, and they are the companies that will reap the harvest when prices inevitably resume their climb.

Intel Beats Forecasts, But 2015 Poses Challenges

Intel (Nasdaq: INTC) announced earnings Thursday, beating guidance but offering an interesting, although somewhat neutral to bearish, view of 2015.  This is a period of significant transition for chip makers in general, and CEO Brian Krzanich painted an excellent picture of what will drive that market for good or ill in the coming year.

Over the past couple of years, there have been three primary markets in that arena: PCs, Tablets, and Phones.  To those broad categories, we can add Wearables, and a new term, "Phablets."  What's a phablet?  Think in terms of the Samsung Galaxy Note - a cross between a phone and a tablet.  So here we have the submarkets in which Intel and other chip manufacturers will compete in 2015. 

PC sales, at least according to Intel, are expected to be flat over the coming year.  That's not really surprising, but I'll be watching the forward guidance from Dell and HP for some confirmation on that front.  Certainly, the ultrabook and 2-in-1 laptop/tablet hybrid will push the PC market a bit, but the chip margins there are still somewhat prohibitive.  Both are expected to exploit Intel's Core-M chip, based on the 14-nanometer spec, but Intel is still suffering from the anticipated high start-up costs associated with that new technology.  The margins will improve through 2015, but you may not see that improvement until the second half of the year.  Still, it's a leader in the market, and Intel stands to benefit from it if demand for the laptop or tablet improves.

A large area of growth worldwide is in the cell phone space.  There is rapid product turnover, and the technology built into new phones is growing exponentially.  Here is where I think Intel's SoFIA technology will shine.  SoFIA takes a dual-core Atom Silvermont processor set into a 28nm system-on-chip (SoC) configuration, and integrates that with a 3G MODEM.  Now, in most of the US, 3G is a bit long-in-the-tooth, and consumers typically want 4G LTE technology on their new phones.  Intel is delivering that in the first half of 2015, and they already have a nice deal in hand with Samsung.  As this price-point drops, Intel stands to benefit tremendously.

I have some reservations about the phablet concept, though.  Bridging the gap between the footprint of a traditional smartphone and the footprint of a tablet, the phablet seeks to increase overall appeal to the consumer of both markets.  I'm not convinced.  Yes, I'm aware that Amazon stated last year that they see consumers asking for either a smaller tablet or a larger phone, but I struggle to see where something the size of a Samsung Galaxy Note can truly be practical in the phone space.  I may be proven wrong, but when I shopped for a phone last year, I chose the Galaxy S3 over the Galaxy S5 simply because the S3 had a smaller footprint and fit better on my belt.  I hear similar comments about phone footprint anytime a group of us tech-heads gather for lunch or dinner and compare our newest toys.  The large phone footprint is a problem, and I don't think it's a long-term survivor.  Whether it's short-term enough to drive Intel's profits in 2015 is outside of my comfort zone, so for me this one's a pass.

The wearable market is another area that leaves me a bit squeamish.  Yes, they are popular, and sales of wearables like the Fitbit have soared.  Unfortunately, the word "fad" keeps bouncing around in my head every time I see one.  At the end of the day, it's going to come down to how useful the consumer finds the data being provided by the wearable and so far I'm not reading much that's positive on that front.  Talk of the FDA regulating the apps that store and present that data also concerns me.

What it comes down to in 2015 was very nicely summarized by Krzanich: "We'll grow at the rate the market does."  He's right.  The question for us is whether or not Intel is a good fit for our portfolios today.  It's currently trading just over 17 times earnings, and it's also only 4% off its 52-week high.  Dividend yield is currently 2.5%, which isn't bad in today's low interest rate market, but once rates start to rise that yield is going to start to look very unattractive.  As much as I like this stock, I'm just not sure it has much room to run in the first half of the year.  I'll feel a bit more comfortable when I see its margins drop as they expect in 2Q15, and I'd really like to see what Samsung has to say about their vision for 2015 in the phone and tablet space.  The same is true for my interest in Amazon's forward guidance since they're the other major player in non-Apple tablets. 

Interestingly, a number of analysts raised their price targets for Intel following this earnings announcement, and that may give the stock a short term boost.  For a portfolio addition as opposed to a short-term trade, however, I'd like to see either a pullback in price or some indication for the end-buyers of Intel chips that there will be sustained growth to warrant a higher stock price.  I'll keep INTC on my short-term trading watch list, but for now, it's not a part of my longer term investment portfolio. 

Consumer Confidence Soars, But There is a "But".

The University of Michigan's Consumer Sentiment Index soared to an 11-year high on Friday, tipping the scales at a whopping 98.2%.  (Bloomberg: Consumer Sentiment in US Surgest to 11-Year High.)  The economists surveyed were expecting a value of 94.1%.  That they were so far off the mark, coupled with statements cited in the article, demonstrates a bit of a disconnect between the economists and a variety of the numbers.

It is not surprising that consumer sentiment soared.  When it comes to spending, what influences the perception of the consumer the most is what is staring them in the face at virtually every major intersection: the price of gas.  Next to gas prices, consumers are highly attuned to what they spend in the super market.  As we've seen, the price of gas is in free-fall, and prices in the stores are relatively flat.  Thus, consumers are happy for now.  They are, however, also very skeptical, but more on that in a moment.

The other aspect that impacts the consumer's economic viewpoint is job security.  Here is where I don't believe the picture is as rosy as economists would have us believe.  We're into January now, which means much of the cyclical job loss has peaked.  Consumers, for the most part, are comfortable thinking that, if they made it through December with their job intact, then there's a good chance they'll continue to be employed at least to the summer. 

The number that is always staring them in the face is the unemployment number, currently at 5.6% nationally.  Of all of the meaningless statistics that the government releases, however, this has to rank near the top for "worst of breed."  The true measure of the employment situation is the Participation Index, not Unemployment, and as of December - the January number isn't out, yet - that figure sat at an abysmal 62.7%.  It's the lowest value since 1978 - a period of post-Watergate economic stagnation and the start of economic distress that would last another 5 years.

One major difference between now and 1978, however, is that the Participation Rate was improving steadily then.  The slope of that graph was positive, whereas today it's negative.  Today, the Participation Rate is growing steadily worse.

Participation Rate - 1970 to Present


There is a bit of a stabilization towards the end of 2014, as you can see in the graph, but the job picture is not good at all.  There are certain industries, in fact, where it's dismal.  Ask yourself if it's possible for someone to do your job out of a remote location (i.e. India) and if the answer is "yes" then you are at an extreme risk of job loss.  It's as simple as that.

Look at the extreme disconnect between this graph, and the statement made by senior US economist Brian Jones: “We continue to generate jobs at a fairly rapid clip, and what you’re also seeing is consumers’ response to what I call a tax cut from lower gasoline prices. That frees up a lot of spending and that means they can purchase other goods and services.” 

One glance at the Participation Index will tell you that, if jobs are being created, they certainly aren't going to Americans in search of work.  That number is in free-fall, and as long as we continue to outsource our jobs to the third world, and as long as we continue to import h1b workers from the third world, the job situation in the US will continue to worsen.

As to the lower price of gas freeing up a lot of spending on goods and services, well, where is it?  The retail sales number for December was a disappointment.  This leads to my comment earlier regarding the skepticism of the consumer.  Yes, gas prices are down, and yes, consumers have noticed it.  But here's the big "But."  Consumers do not believe it's here to stay.  Very few consumers understand what drives the price of oil, and fewer still understand how that - and other factors - impact the price of gas at the pump.  Instead, conspiracy theories abound.  Many believe it's manipulated by the government, many believe that it's set by "big oil", and most believe that the price will skyrocket back up to $4 per gallon almost overnight.  What consumers are not doing is looking at the extra $10 or $20 in their pockets at the end of the month as a reason to go out and buy something else.

Richard Curtin, the Michigan Survey director, made an interesting statement which calls into question the validity of the survey itself: “Gains in employment and incomes as well as declines in gas prices were cited by record numbers of consumers.  More consumers spontaneously cited increases in their household incomes in early January than any time in the past decade.”

That statement troubles me for two reasons.  First, we've seen that employment in general is not increasing.  We know that the number of people working part time, instead of full time, has increased, and we can see from the graph that the number of people that have a job (out of the pool of people that want a job) is at a 36-year low.  Think about that!  The employment conditions have not been worse in almost 4 decades, and they continue to decline!

Second, we know that income is not increasing.  It's barely keeping pace with inflation.  Hourly earnings only increased by 1.7%.  Inflation is sitting today at 1.6%.  Factor in the increased cost of benefits in 2015, and families are losing money, not gaining it.  About the only way to increase your income today is to go out and get a second or third part-time job - certainly not something that any consumer would view as a positive.

So yes, the consumer confidence number did increase significantly.  Don't read too much into it.  That increase is temporary exuberance driven entirely by the temporary sharp decrease in gas prices.  Until I see tangible proof that consumers are doing anything with that extra money beyond paying down credit card and loan debt, I'll continue to treat the index as an interesting but relatively insignificant portion of the global picture.

Friday, January 16, 2015

Does 2015 Present a Perfect Travel Opportunity?

The Euro versus the US Dollar plunged to a 10-year low today and all signs indicate it will continue lower if the ECB implements some form of easing as they are expected to do next week.  We've seen multi-year support in the 1.20 range, however today it has recently driven through that support and today dove under the 1.15 mark with no signs of looking up.  Given global weakness and the prospects for some form of QE coming out of the ECB, there's no end to this trend in sight.

USD to EUR 10-Year Chart


The exchange rate on the Euro alone is enough to entice travelers to look at European vacations in 2015.  This is the best exchange rate we've seen for the US consumer in well over a decade.  Making it even more attractive now, though, is the decline in oil prices that are helping keep airline ticket prices in check.  Some forecasts suggest an overall decline in ticket prices for 2015, at least according to Expedia. 

This is great news for traders in several sectors, especially if overall prices in the US remain low, gas prices remain low, and consumer confidence increases.  We've already discussed Alcoa's views regarding overall growth in the airline industry, and what we see in the exchange rate supports that view.  The airlines themselves should benefit since demand from increased tourism will offset any downward pressure on price, thus increasing their margin when combined with falling fuel prices. 

With increased tourism and demand for air travel come increased aircraft orders for the major carriers.  There's also the potential for increased maintenance requirements on the aircraft, so the suppliers of parts will benefit.  Those airlines that have yet to squeeze passengers into every available nook and cranny will be placing orders to providers like B/E Aerospace for more seats, thinner bulkheads, etc.

Looking a bit further into the future, we see potential with Cuba as well.  It was announced today that some of the travel restrictions there were lifted, making it easier to travel to Cuba without State Department approval provided the reason fits into twelve relatively broad categories.  Unfortunately, tourism isn't one of them, but the writing is on the wall, there.  I will be surprised if tourism isn't added to the list during the current presidential term.  Cuba as a tourist resort provides a host of trading opportunities, so we'll be keeping a very close eye on political developments on that front.

For now, I'm watching the forward guidance provided by key players in the Materials, and Industrials.  Consumer Discretionary will also provide a clue as to where the potential traveler is spending their money and where we think that is heading.  The bottom line is that, even those of us that don't play FOREX, we have some excellent equity trading opportunities coming out of the falling Euro.  Keep an eye on forward guidance in these sectors and trade accordingly.

Inflation, Industrial Production Show Slight Declines

The Consumer Price Index (CPI) for December came in at -0.4%, the greatest decline since 2008.  The Core CPI - which excludes the cost of food and energy - came in flat at 0.0%.  The rapid decline in the cost of oil and gas has clearly had a dramatic impact on prices.  What the Core CPI is telling us, though, is that inflation - now only 1.6% - is showing no signs of approaching the 2% level that the Fed is reportedly using as their bellwether.  The weakness in prices is not unexpected - the numbers were in-line with market surveys - but they are now fueling a very active debate around the timing of interest rate increases.

General consensus points towards a late 2nd quarter increase in interest rates.  The weak economic numbers throughout the first half of January, however, are increasing speculation that the interest rate hikes may be delayed well into the 3rd quarter, and even as late as a mid-4th quarter increase.  Nothing that I've seen thus far would lead me to believe that rate increases will come in the first half of the year.  FOMC has a two-day meeting the last week of January, and the weak data to date should have even the hawks on the committee taking a wait-and-see position.

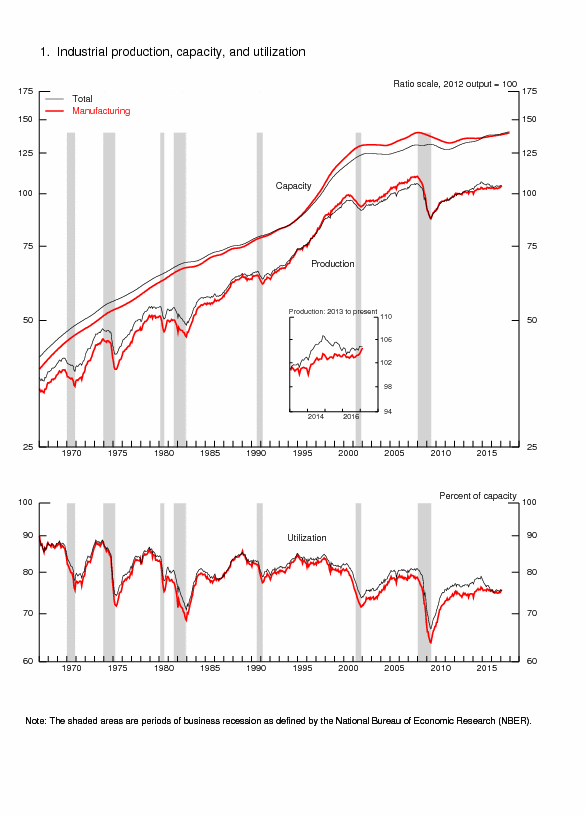
On the production side, the numbers released this morning were somewhat mixed. Industrial Production decreased 0.1% in December.  That decrease follows a dramatic 1.3% increase in November. The bulk of the decline was in the Utilities sector, though, where heating demand dropped significantly.  When you take utilities out of the equation, industrial production experienced a 0.7% increase.  That's still a significant decline from the November numbers.

One encouraging note was a 1.4% rise in construction supplies.  This will warrant a closer look, since we may have a trading opportunity in that sector.  Defense and Space equipment rose 0.4% as did the production of materials with gains being seen in all major sectors.

The slope of Industrial Production over time is encouraging.  It's showing healthy year-over-year growth with no signs of the flat and downward slope that serves as a harbinger of a recession. (Look at the months preceding recessions in the charts below.) This adds fuel to the argument that current weakness in the overall economy is short-term and a reflection of the global picture, not the domestic picture.  What does concern me, however, is the strength of the US dollar.  While our production is strong, our ability to export is going to weaken unless we can tame the growth of the dollar.  That's another reason I don't believe a rate increase is imminent.  With the current strength of the dollar, a rate increase will add further pressure on our exports.  I just don't see the Fed ready to impose that pressure, and I don't see the key numbers - PPI, CPI, Retail Sales, and Consumer Confidence - moving in the direction the Fed needs before an increase is possible.

Industrial Capacity and Production

Thursday, January 15, 2015

Weak Retail Sales, PPI May Delay Fed Move

It's only January, and one month's data does not a trend make.  Still, yesterday's dismal Retail Sales report for December, coupled with today's weak Producer Price Index (PPI) report will certainly give the Fed pause as it considers when and how much to raise interest rates. 

Yesterday morning's Retail Sales report for December showed a dramatic decline of 0.9%, the weakest number since January 2013.  While that sharp a decline may be an aberration, it's difficult to dismiss amidst all the other foreboding signs that the economy may not be as robust as first thought.  Coming at a time when gas prices have been falling dramatically, though, it is certainly cause for concern, especially if we don't see a decent rebound next month.

The Producer Price Index (PPI) reported today, showed similar weakness, declining another 0.3%.  This index has now fallen for four consecutive months, with December's decline being the steepest since 2011.  While the price decline would signal good news for consumers, it will also signal to the Fed that inflation is not threatening to rise anytime soon.  With these two numbers - Retail Sales and PPI - in hand, tomorrow's Consumer Price Index (CPI) should prove very interesting.

The US dollar continues to run very strong, and that strength is not going to help US exports.  This is yet another reason I believe the Fed will further delay any interest rate increases.  With inflation not showing any signs of challenging the 2% mark, and with a strengthening dollar adding further pressure overseas, I just can't see the Fed changing their posture in the first half of 2015.

What all this means for the broader economy is hotly debated.  There's a widespread belief that consumers are spending the money saved from the plummeting cost of a tank of gas, however I'm frankly not seeing any evidence of that.  I've discussed that with people I encounter in various settings, and have yet to hear actual consumers confirm that they see this as a windfall available to spend at will.  What I do hear is that people are using it to pay down bills, and occasionally I hear that they're saving it, but that's about it.  They're not spending it to the point where it is noticeable in the numbers.

This makes sense when you stop to think about it.  The dropping price of gas is most beneficial to folks that are living close to paycheck-to-paycheck.  It makes sense that they are most likely to have credit card or loan debt that needs to be paid down, and they're taking advantage of that little extra to do just that.  They're not going out and buying something extra.  Folks with little-to-no debt don't really notice the difference other than to mention by the water cooler that they just spent less to fill up their tank.  This group was already spending what and when they wanted, so the extra few bucks isn't making a difference in their habits.

What is definitely making a difference is the lack of compensation in the form of merit increases on the job, and the erosion of corporate benefits.  The price of health care increased dramatically for the average worker again this year, and - based on current surveys - merit increases are barely keeping pace with inflation.  The drop in the price of gas is merely keeping the average worker's overall income on par with last year's, given increased benefits costs.

With each passing week, I'm increasingly bearish on the prospects for 2015.  There's now bipartisan talk in Congress about a federal gas tax increase to replace lost revenue from the declining price of gas.  Unfortunately, that will only exacerbate the impact when oil and gas prices inevitably resume their normal upward trend.  Europe's continued weakness, coupled with a lackluster growth forecast (compared to prior years) for China and India have me concerned about global drag on the US economy.  Draghi's inability to send clear and consistent signals about the ECB's plans aren't helping.

For now, I'm taking a neutral to bearish posture in my trading, and I'm paying very close attention to the forward guidance in various sectors, trying to determine where there may be trade-able strength.  Or trade-able weakness, for that matter. There's nothing wrong with going short in a down-turning market.  Let's see what tomorrow's CPI report signals.  I'll be very surprised if it doesn't confirm the other reports from this week.

Wednesday, January 14, 2015

JPMorgan's Dimon Calls Regulators to Task

It's obvious by now that JP Morgan Chase (NYSE: JPM) failed to meet analyst expectations in their 4th quarter and year end earnings announcement, released today.  At issue was a 26 cents per share miss related to legal fees that were almost a billion dollars more than analysts had forecast.  Given that their legal fees were almost $8 Billion less than 2013, one might argue that this was an analyst failure and not a JPM failure, but for the moment, we'll let that debate slide.  What is worth discussing, however, were CEO Jamie Dimon's harsh criticisms of Federal Regulators that are plaguing the entire banking industry.  (Bloomberg: JPMorgan CEO Dimon Says Overlapping Regulators Assault Banks)

"Banks are under assault by the Regulators," Dimon stated today.  During the conference call, he shrugged off reports questions for more details with a simple, "You've got to be kidding me."  Dimon is spot on accurate in this assessment.  Since the 2008 Financial Crisis, regulators have swarmed the banking industry like sharks chasing chum.  The amount of needless overhead they have forced banks to incur now has the potential of creating the next crisis.

As Dimon correctly stated, “We have five or six regulators or people coming after us on every different issue.”  In the past, issues would be handled typically by a single regulator.  The amount of bureaucracy this feeding frenzy has generated in the banks is a severe drain on the bottom line, and it threatens the financial well-being of the industry itself.  Worse yet, the type risks this new wave of regulator is uncovering have virtually nothing to do with either the financial or security related risks inherent in a 21st century financial business.  They are doing a great job of forcing banks to check boxes in the regulatory risk spreadsheets, but they are doing nothing to identify real risks that would warrant oversight and closure.

Capital requirements driven by seemingly arbitrary and rapidly changing regulatory requirements are also severely impacting the ability of banks to drive revenue.  JP Morgan alone is now required to raise an additional $20 Billion in capital by 2019.  Similar requirements are straining and constraining other large banks that would under other circumstances, fueling the economy. 

To compound problems, the regulators are now using their disproportionate clout to extort exorbitant fees - in the forms of fines - from banks that, in some cases, did precisely what they were requested to do.  JP Morgan is another example of this when, during the banking crisis, they agreed to acquire Bear Stearns and Washington Mutual.  Their reward for assisting the government in providing this shareholder-funded bailout was to be fined for actions that Bear Stearns and Washington Mutual had executed prior to the JPM acquisition.

Dimon's attack on the predatory practices of today's regulatory bodies was right on the money.  For there to be a fundamental shift in this practice, however, we need to see other reputable banking CEOs continue that attack.  Dimon cannot stand alone if there is any hope to force the regulators to back down.  Short of that, however, the regulators will remain one of the greatest threats to the health of the financial industry.  It's a problem that is felt by every bank in the US today, and if left unchecked, it will result in unnecessary failures.

Tuesday, January 13, 2015

What's Up - Or Down - With Oil?

Financial headlines for the past couple of months have focused on the plunging price of oil, and the impact those oil prices have had on various segments in the market.  As you would expect, there's been some major league speculation on what's causing the decline, but at the end of the day it really comes down to the old fashioned supply and demand curve. 

There is no question in anyone's mind that oil supply is driving extreme downward pressure on the price.  OPEC is in political disarray and they are no longer able to exercise the muscle they once had in controlling the supply side of the equation.  The Saudis are pumping oil as fast as they can pull it out of the ground.  Iraq is once again a player in the oil market, and their supply is an added bonus.  The US is poised to become the world's largest oil producer.  The North American (US and Canadian) shale fields are demonstrating amazing potential.  So yes, there is certainly a glut of oil on the market today.

What about the demand side of the equation?  To answer this, we have to look at two aspects of demand.  The obvious one, and the one most often cited, is demand for the finished product.  With Europe once again heading into recession, there's a decrease in end-product demand there.  Demand in China is reportedly down, although US demand is reportedly up a bit.  That's not surprising given the very attractive gasoline prices across the nation.

That, however, is not the "demand" that's currently driving that side of the equation.  Rather, we need to look at the demand for the raw product - crude oil - not only the demand for the finished product.  US Oil Refineries, as of last week, are operating at 94% capacity.  That's about as close to full capacity as you can get, and that will continue until April when refineries begin their semi-annual maintenance cycle.  Demand for oil, at least in North America, cannot increase simply because there is no additional capacity to refine it.  With North American demand being a constant in this regard, the increasing supply can do nothing but drive the price down.

The refinery side globally is a bit different.  Refining capacity is increasing globally, with an additional 8.3 million barrels per day being added by 2019, and it's not currently operating at or near capacity.  There is where end consumer demand is coming into play because European and Middle Eastern oil is available however the demand for the finished product is down.

What threw the pundits into a tailspin today was a change in the relationship between West Texas Intermediate Crude (WTI) and North Brent.  Typically, WTI trades at a discount to North Brent, however today the two prices converged.  For a brief period, they even reversed with Brent trading lower than WTI.  The question on the table is what to make of that, and several pundits are pointing to weakness in the European economy as the answer.  I'm not so sure.  Rather, I'm speculating that this is a bit of a political reaction.

Now that we are into the second week of the new Congress here in the US, bills to move the Keystone Pipeline forward are starting to surface.  For the first time, the Republican controlled Senate has a super-majority in support of bringing the legislation to the floor.  (They have 63 votes - 3 more than the 60 needed.)  Now, that is still 4 votes shy of the number needed to override the threatened Presidential veto, which means this bill is going to live or die based on the amendments that are attached to it. 

The Democrats have already stated they will be attaching climate change related amendments to the bill.  The substance of those amendments haven't been discussed yet, however they will certainly be countered by Republican amendments equally distasteful to the other side.  One amendment that has been discussed would allow a resumption of US oil exports.  Now, trading based on amendments that have yet to make it onto a bill let alone having passed a vote is folly, but short term reactions tend to do just that.  The brief stabilization in WTI without a corresponding stabilization in North Brent coincidentally coincides with the news about Senate support for the bill and the various amendment proposals that will likely be attached.  Exporting WTI, especially with the excess global refining capacity while the US is at full capacity, will stabilize the price and likely assist in moving that commodity back into a normal trading pattern.

The behavior of these two commodities should be closely watched.  Once oil prices stabilize, there is a tremendous investment opportunity across that entire sector.

A Potential Rebound Play in B/E Aerospace

Shares in B/E Aerospace (NASDAQ: BEAV) were hammered in the fourth quarter of 2014 after the company announced they would spin off its consumer management segment into a new company called KLX (NASDAQ: KLXI).  The beat-down continued following their third quarter earnings announcement despite some very good numbers and very positive forward guidance. 

In that conference call, they raised their guidance for the remainder of 2014 by 10 cents per share, expecting $4.45 per diluted share.  That's a 25% increase over the previous year.  They forecast double digit earnings and revenue growth for 2014, and also forecast double digit earnings and revenue growth for 2015.  The drubbing their shares took at the time does not match the economic health and growth potential of the company.

Since mid-October, the price of their shares has improved in fits and starts.  They are trading in an upward channel and have now broken through some resistance at $59.50.  In the short term, they have the potential to test resistance at $64, and depending on their results and guidance released in their January 28th 4th quarter earnings call, they have the potential to retest $70. 

The outlook for the company is certainly optimistic.  We heard from Alcoa yesterday that aerospace production is expected to grow in 2015.  Regardless of which aircraft manufacturer gets those new orders, B/E stands to benefit.  B/E Aerospace sells the interior components of both commercial and business jets, providing the bulkheads, seats, and even the coffee makers that are installed in aircraft large and small.  While Boeing and Airbus battle for the large aircraft manufacturing orders, B/E rides the strength of that market by selling their wares to either company. 

Looking at the irrational reaction to their October release, there is certainly some risk to being long in this stock on January 28th.  Protecting a long position with protective puts would be a wise choice if you want to hold over that announcement as we've seen that, even with good earnings, good revenue, and improved forward guidance, this stock can still be punished.  In the medium to long term, though, B/E Aerospace appears poised to capitalize on strong growth in the Aerospace industry through 2015.

BEAV Daily Chart

Monday, January 12, 2015

Alcoa Signals Strong 2015 Aerospace Growth

I mentioned a couple of days ago that the most critical component of a company's earnings report is the forward guidance they provide.  Rarely is this included in the earnings news release, but it's always available in the conference call following the release.  The companies website - along with several other internet sites - provide a transcript of that conference call, and it's always worth scanning for broad market information.

Alcoa (NYSE: AA) reported fourth quarter 2014 earnings after market close today.  They reported $6.4 Billion in revenue, beating market expectations of $6.02 billion, and excluding one-time charges, they had earnings of 33 cents per share, well ahead of analyst expectations of 27 cents per share.  Both of these numbers signaled a successful 2014 for the aluminum giant.

The most important information, however, was gleaned from their conference call.  While we're certainly interested in how we believe the company will fare in 2015, we should also pay attention to what they are telling us about the domestic and global economies and what they signal for other industries.  In this case, the forecast was fantastic for the aerospace industry where Alcoa is expecting aerospace sales to increase 9-10%.  They see this demand in large commercial aircraft, regional aircraft, and in aircraft engines.  This is an indication for us to keep an eye on that sector for potential investment opportunities.  Here is a link to the companies in the aerospace sector for your convenience.

On the automotive front, Alcoa is projecting global production of 2-4% "driven by replacement demand and low lending rates in North America and both the growth of the middle class and clean air regulations in China."  I find the phrasing of that statement interesting.  Low lending rates in the US should help the US auto industry, but of extreme interest is their forecast of the growth of the middle class in China.  Chinese growth is a main driver in many industries, and it's encouraging to see Alcoa's statements to that effect.  We will keep an eye on the automotive industry, although 2-4% isn't really making me yearn to own stocks in that sector.

Alcoa made some very strong projections for the building and construction market, seeing global growth of 5-7%.  They caution that they expect a decline in that market in Europe, however, which implies that the global growth will be primarily in China and India.  That matches our expectations that Europe is likely heading into recession, but their decline will be well offset by strong growth in Asia.

Projections for the trucking and freight market in North America show strong growth.  That hints at strength in the transportation sector as well as the consumer staples and possibly the consumer discretionary sectors.  Trucking and freight companies need something to ship, and if growth is strong, it means consumers and businesses are buying.  That's good news for overall economic health in the US.

Interestingly, they saw the aluminum market holding steady at 7% growth in 2015.  There are several new players in the global aluminum market, and they will be adding pressure to the price (and thus the revenue side of Alcoa's financial equation) but continued increased demand in China should offset that pressure.

Overall it looks like Alcoa is forecasting sustained growth in Asia for 2015, and that's good news for the overall US market.

Sunday, January 11, 2015

The Economic Week Ahead - January 12 to 16

Here are the market influences we'll be watching for the week of January 12-16. 

External Impact

Oil -- Oil prices are likely to remain volatile.  While it's my opinion that the price of oil is having only a marginal impact on the market to date, and that other factors have generated the high volatility, there are many pundits that say otherwise.  Be aware that we have yet to see oil either stabilize or rebound, so volatility in that commodity remains in play.

European Weakness -- The closer we get to the January 22 meeting of the European Central Bank, the greater the influence the weak European economy will have on the market.  There is a possibility that the ECB will announce their own version of QE in that meeting, so expect market volatility leading up to it.

Greek Elections -- With the Greek's leftist Syriza Party holding the lead heading into the January 25th elections, there is significant uncertainty into that nation's economic future and the impact it will have on the Eurozone in general.  Syriza favors renegotiating the 240 Billion Euro bailout Greece received from the ECB and IMF, and they also want to cancel a portion of that debt.  Expect increased volatility to ride the wave into the Greek elections.

Options Expiration / Martin Luther King Day -- Friday will see January options expiration at market close, and that tends to generate some extra volatility.  The market will be closed the following Monday - Martin Luther King Day - so we can expect to see even more volatility and potentially some downward pressure at the close on Friday as short-term traders take money off the table for the long weekend. 

Earnings to Watch

JPMorgan Chase (JPM) reports Wednesday, 1/14 at 7:00 AM.
Wells Fargo (WFC) reports Wednesday, 1/14 at 8:00 AM.
Bank of America (BAC) reports Thursday, 1/15 at 7:00 AM.
Charles Schwab (SCHW) reports Thursday, 1/15 before the open.
Citigroup (C) reports Thursday, 1/15 before the open.
Intel (INTC) reports Thursday, 1/15 after the close.
Goldman Sachs (GS) reports Friday, 1/16 before the open.

Significant Economic Data Releases

Monday - 12 January

No data reported.

Tuesday - 13 January

The Treasury Budget report will be released at 2:00 PM.  This report, however, is typically not of any significance related to market action.

Wednesday - 14 January

Retail Sales (8:30 AM) - This is the big one for Wednesday.  This will tell us how well retail stores did in December, and will provide insight into broad consumer spending patterns.

Export Prices, Import Prices, and Business inventories are also reported, however they are not watched as closely as the retail sales announcement.

Thursday - 15 January

Producer Price Index (8:30 AM) -- This is Thursday's big one.  This report identifies the wholesale costs of goods.  The number we're most interested in is the Finished Goods number as that most closely tracks what consumers will ultimately pay for the product.

Philly Fed Manufacturing Business Outlook Survey (10:00 AM) -- This is a survey of manufacturers in the Philadelphia Fed's regional jurisdiction.  It provides insight into the economic trends including wages, earnings, inventories, etc. specific to that region.

Friday - 16 January

Consumer Price Index (8:30 AM) -- The CPI is the most widely cited measure used for inflation.  With QE3 over and the market waiting for some indication as to when the Fed will begin raising interest rates, this number will be watched very closely.

Industrial Production / Capacity Utilization (9:15 AM) --These numbers are also used by the Fed to gauge inflationary pressures, although the utility component can be very weather dependent and thus highly volatile.  Still, as the market tries to read the Fed's mind regarding interest rates, this number will be closely watched.

Is KRFT Poised For Action?

On December 18, Kraft Foods (NASDAQ: KRFT) announced the appointment of John Cahill as its new CEO to replace retiring Tony Vernon.  The news was well received on Wall Street, and the stock reacted with a $0.74 breakaway gap at the open, and then soared for an additional $2.80 to close at $62.84.  Of technical significance, the stock gapped above resistance on very high volume and it never looked back.  The 19th saw volume almost as high as the 18th, and the stock continued to rise.

Chartists will recognize a very well defined flag pattern, complete with a rapid 10% rise in the flagpole, followed by a downward shaped flag that ran for almost two weeks.  The bottom of the flag is imperfect thanks to the turmoil of last week's market action, but overall the pattern looks sound.  Heavy volume returned on January 7th with a strong upward thrust, and it continued on the 8th when KRFT closed above the flag pattern. 

If the flag pattern holds true - and 64% of them do on a bullish break in a bull market - then we could be looking at a price target of $66.27 in the short term.  The only blinking caution lights are a resistance line that has formed in the $64.25 range, and the fact that the resistance line is straddling the stock's 52-week high.

Kraft reports earnings on February 11th at 4:00 PM, so we may see a run to the pattern top as that date approaches.  Cahill's first conference call and forward looking statements will be interesting to watch, and that will determine the direction the stock takes from there.  The stock last paid a dividend of $0.55 in December and is expected to announce a similar dividend for late March or early April. 

On the fundamentals side of the analysis, KRFT carries a lot of long-term debt as of year-end 2013, and their cash flow degraded that year.  The February earnings release will provide insight into whether this is a short term trade or if it becomes a longer term investment under Cahill's leadership.  For now, chartists will want to take a look at the flag pattern and decide if the time is ripe for a short-term play, while fundamentalists will want to monitor the February earnings release for an indication of the direction Cahill will take the company.

Kraft Foods (KRFT)

Saturday, January 10, 2015

Market Carpet View of Sectors

When searching for medium to long term trading opportunities, especially around earnings season, I find it both interesting and rewarding to watch market sectors that are under-performing the rest of the market.  These under performers may provide some bargain basement entry opportunities, provided the underlying company is well managed and has significant growth potential.  Sometimes a market sector dog is a dog for a reason, but many times they have been beaten down well past a justified level and they now present a great opportunity for profit.

When looking for good entry points on fundamentally sound stocks, don't underestimate the impact overall market direction and overall sector direction have on the individual equity.  As we've seen time and again with strong market sell-offs, the force of the market as a whole will beat down stocks that are fundamentally very strong.  These become excellent buying opportunities since we can enter a long position at an artificially deflated price.

StockCharts has some excellent free charting tools that assist in this research.  My favorite "at a glance" view across all S&P 500 sectors is a Market Carpet chart as seen here:

Market Carpet Sector Map


The sectors I'm most interested in watching this earnings season are Financials and Utilities.  They've been beaten down for the past quarter and they may provide some interesting investment or long-term trade opportunities should this quarter's earnings demonstrate improvement.  Consumer Staples and Energy are the other two sectors that have been ravaged, and I'll also be keeping an eye on opportunities there, although in the case of Energy there needs to be some upward movement in the price of oil before I'm comfortable going long on stocks in that sector.

Another advantage of the free Market Carpet charts is the ability to zero in on a specific sector.  Here is the Market Carpet chart of the Financial sector.

Financial Sector Market Carpet


Unlike the overall sector view, to see the individual stocks in the sector you must hover over the block in which you have interest. The chart, though, does give you a nice "at a glance" view of all stocks in the sector, allowing you to zero in on the ones of most interest.

Watching the earnings announcements for the bottom five, two of which are reporting next week, we may have an early signal as to the overall direction this sector will take in 2015.  Strength in the bottom stocks may provide an opportunity to go long individually, or even to take a long position in the Financial SPDR (XLF) or the Financial iShares ETF (IYF).  Weakness in the top five would be a reason to avoid going long in this sector for the time being.  The same philosophy holds true for the other sectors that have been beaten down in the past quarter.

Remember, to "buy low and sell high" you must first identify stocks that are fundamentally strong, but have undergone a pullback or even a correction.  This doesn't necessarily apply to the very short time-frame trader who is only interested in daily momentum, but it's very applicable for the long-term trader or the investor seeking to hold the stock for an extended period.

Welcome to Earnings Season 2015

The last week in the stock market certainly provided a very brief but very exciting wild roller coaster ride.  Five consecutive days of triple digit swings culminated in a rather unsurprising 170 point drop into the weekend.  When volatility rides as high as it did this week, short-term traders simply do not want to be long heading into a weekend, and we saw that with the large number of sell orders heading into the close on Friday.  The pundits provided a litany of reasons for the wild swings, ranging from fears over oil prices, fears over Greece leaving the Eurozone, fears over the Russian economy, to fears over - well, just insert your fear here.  You get the drill.

Let's face it.  In the new global economy, there will always be fears adding downward pressure in the short term.  Some market someplace will always have debt issues, there will always be turmoil in some part of the globe, and some sector in the economy will always be experiencing a pullback or a correction.  It's a fact of economic life.  So what should we be focused on in the weeks ahead?  Fundamentals.  At their very core, stocks are based on the fundamental economic health of individual companies.  Understanding how all of the external pressures impact the bottom line of those companies is our guide to determining if a drop in stock price is a warning sign to flee for the hills or if it is a perfect buying opportunity at a nice, low price resulting from the irrational fear of others.

The week ahead will provide a very good glimpse into the health of this earning season.  Wednesday and Thursday will see some very important earnings announcements that will provide a good indication as to the overall health of various sectors.  On Wednesday, JP. Morgan reports at 7:00 AM, and Wells Fargo follows at 8:00 AM.  On Thursday, Bank of America leads the way at 7:00 AM, and the others to watch on the financial side are Charles Schwab and Citigroup.  These are all financial stocks that will provide insight into the banking and brokerage sides of the market.  The one other stock to watch, though, is Intel.  They report after market close on Thursday, and they may well be a harbinger of the technology sector's performance.

Remember, there are three aspects of an earnings announcement that are important.  It's not just the final p&l number that we care about.  Of course, we want to watch the earnings number, certainly.  That is an excellent indicator not only of the profitability of that company in the prior quarter, but it also gives you some insight into the accuracy of analyst expectations for that company and that sector.  Did they meet or beat expectations?  If they missed, is that an indication of corporate under-performance or were the analysts way off in their analysis of that industry?

Pay attention to their revenue stream in comparison with prior quarters and with the same quarter the previous year.  If earnings improved, but their revenue stream didn't, then is there really a potential for continued growth?  Expenses can only be cut so far, as they represent a finite component of the balance sheet.  We really need to see improving revenue, since there's theoretically no limit to that side of the equation.  I'm always cautious about companies that show strong earnings on weak revenue.  There's a limit to their growth potential.

Most importantly, pay close attention to forward guidance.  What pressure does the company foresee over the next year and what are their plans to counter that pressure?  If earnings or revenue were less than expected, what are their plans for improvement?  Is the CEO another Baghdad Bob screaming "all is well" while the building is crumpling around him or has he given us a very candid assessment complete with a solid growth plan?  Of all the components of an earnings announcement, this is the one to which I pay the most attention.  As either a trader or an investor, I'm far less interested in where a company has been than I am in where that company is going.  Entering a long or short position on a stock is a forward looking position, so we absolutely must know that company's plans for the future.

It's early in the earnings season, and we can expect a bit of volatility.  By paying close attention to these early announcements, though, we may gain a good sense as to the direction of individual sectors and to the market as a whole.  If Wells Fargo, Bank of America, and Citigroup come in strong, it's a good sign that the banking sector as a whole may report strong, and there may be some excellent short term trading opportunities around subsequent announcements this season.  Likewise, if they are weak, it may be time to go short on some of the weaker players in that sector or, if nothing else, wait for their drop and pick them up at a bargain price a week or two later.

There are some interesting economic data releases coming out this week as well, but we'll reserve that discussion for another post.  Good trading!

Tuesday, October 07, 2008

Fed to Compound Credit Problem

The Federal Reserve today announced that it would purchase US Commercial Paper in an attempt to ease the credit crunch impacting corporations throughout the US. (Bloomberg: Fed to Purchase U.S. Commercial Paper to Ease Crunch.) According to Bloomberg, "The Fed's new unit will buy three-month dollar-denominated commercial paper at a spread over the three-month overnight- indexed swap rate." In addition, the nation's central bank will double its cash auctions to banks, raising the amount auctioned to as much as $900 Billion.

Does this remind anyone of a famous quote from Thomas Jefferson? "The central bank is an institution of the most deadly hostility existing against the Principles and form of our Constitution. I am an Enemy to all banks discounting bills or notes for anything but Coin. If the American People allow private banks to control the issuance of their currency, first by inflation and then by deflation, the banks and corporations that will grow up around them will deprive the People of all their Property until their Children will wake up homeless on the continent their Fathers conquered."

There is little doubt that we are facing perhaps the worst economic crisis since the Great Depression. For the moment, one might argue that the post-Watergate crisis that saw double-digit inflation and double-digit unemployment was worse than what we face today, and if today's crisis were in its final hours I would agree. Unfortunately, we face the dawn of this crisis, not its sunset. If improperly handled, this crisis will yield another Great Depression.

The current spotlight is on sub-prime mortgages, and financial institutions lending significant sums to people that can ill-afford those loans, all on the prospect of being able to sell this bad paper for profit or at worst being able to foreclose on property increasing in value. Truth be told, though, the sub-prime issue is only the tip of the iceberg. The collapse of the housing market did result in the sub-prime issue starting a financial avalanche, but this issue was stacked way atop many other more subtle problems that may well drive us into another Depression.

First and foremost, we are seeing a steady decline in the US job market. The alarm was first raised in 2004 when the AFL/CIO warned that the number of jobs sent overseas had doubled in the past year. In January of this year, the Peterson Institute for International Economics warned that as many as 20 million US jobs out of a 140 million job pool were at risk of off-shoring. That's over 14% of the jobs in the US that are at risk. While our unemployment numbers rise (6.1% as of September 2008), the Consumer Confidence Index continues to barely tread water. Over 25% of the people believe the job market will worsen in the next quarter. That means that 25% of the people are concerned about job security, and based on the Peterson numbers, rightfully so.

Next in line we have rising inflation. The increased cost of food and fuel is crippling most low to middle income homes. Lest we forget, that accounts for close to 95% of the American public. Why is the mortgage foreclosure rate so high? Quite simply, it's because the average American family has had their net income squeezed through rising fuel, home heating or cooling costs, and skyrocketing food costs. That money had to come from someplace, and in too many cases it came from the mortgage bill. This economic crisis will not end as long as the average family cannot afford to pay their basic bills.

This leads us to the topic of debt. The average American credit card-holder is in debt to the tune of $8000, so that's $16,000 per family on average. Tack onto that a mortgage and an auto loan, and it's not hard to see where most of America's income is going. As inflation rose, the number of bills being paid by credit card also grew. Now this credit-card crisis has yet to materialize in the banking industry, but rest assured this crisis will hit home over the next 4-6 months. Credit cards are unsecured loans. As consumers begin to default on those cards, banks will be forced to take write-downs. Who will come to the rescue? You guessed it - the American taxpayer. We've already done it twice, first with the $700 Billion white elephant that just cleared Congress and now by the Federal Reserve's unilateral (and most likely unconstitutional) decision to purchase corporate debt.

If you read that Bloomberg article linked at the top of this post, I'd recommend paying close attention to this one sentence: "Fed officials in a conference call with reporters didn't say how much commercial paper, which hundreds of companies use to finance payrolls and meet other cash needs, it plans to purchase."

Let's ignore the fact that the Fed has no clue how much commercial paper they will purchase. That fact alone bothers me since it's pretty much a blank check being written by the Fed. What bothers me more, though, is that "hundreds of companies use (commercial paper) to finance payrolls and meet other cash needs..." Clearly, the concept of out-of-control debt is not limited to the individual or the family. Companies need to borrow money just to meet their payroll requirements. This issue of debt is rampant throughout our economy. So rampant, that the Fed now feels obliged to offer a unilateral bailout to corporations by purchasing their debt.

So what has the government done to date about this crisis? They've increased debt and they've attempted to make it easier to obtain more debt. In case you've missed it, there's increased talk of yet another interest rate cut to stimulate borrowing. If debt is at the heart of the economic crisis, how are we supposed to believe that increasing debt is going to cure it? Has it not occurred to anyone that the solution is to decrease debt, not increase it?

What was that Jefferson said? "If the American People allow private banks to control the issuance of their currency, first by inflation and then by deflation, the banks and corporations that will grow up around them will deprive the People of all their Property until their Children will wake up homeless on the continent their Fathers conquered."

Amazing foresight, wouldn't you say?


Technorati:
IceRocket:

Sunday, September 28, 2008

Election 2008 - Health Care Issue - Obama Version

The second article in our series of 2008 campaign issues focuses on the Health Care plan proposed by Senator Barack Obama. Details of his plan may be read on the official Barack Obama campaign website.
The Barack Obama Plan


Senator Obama's health care plan emphasizes from the start two points that are at the center of concern for anyone studying a more comprehensive health care solution. Taken directly from his campaign website, the Senator states:

"Under the plan, if you like your current health insurance, nothing changes, except your costs will go down by as much as $2,500 per year.

If you don’t like your health insurance, or you don’t have health insurance, you will have a choice of new, affordable health insurance options."


On the surface that sounds excellent. All of us with insurance would love to see a reduction in costs, while those without insurance are very much in need of some form of affordable coverage. Now, the word "affordable" is very much up for debate since many of those without insurance today can't afford their present bills, let alone anything added on for health care. But for the moment, let's take the statement as written and at face value.

Since the Senator took the time to itemize each of the key points in his plan, I will repeat them hear and comment on each of them. The points I'm listing are directly off his website.

Require insurance companies to cover pre-existing conditions so all Americans regardless of their health status or history can get comprehensive benefits at fair and stable premiums.

Most company sponsored health care plans do have a pre-existing waiver built in during the annual open enrollment period. As we age, this becomes a necessity, and it's good to see some recognition of this requirement built into a health plan. Mandating it, however, will result in an increase in insurance premiums. Once insurance companies are forced to accept pre-existing conditions by default, the natural response will be to raise the cost for everyone.

Create a new Small Business Health Tax Credit to help small businesses provide affordable health insurance to their employees.

This point is necessary if we're going to require small businesses to provide health insurance benefits, assuming they are sharing in the cost of that insurance. Small businesses are at the heart of local economies, but all too often they exist on a shoe-string budget, surviving from month to month. A mandate from the government that forces a significant increase in their expenses must come with some government protection in the form of tax credits. I fully support this point in the Obama plan.

Lower costs for businesses by covering a portion of the catastrophic health costs they pay in return for lower premiums for employees.

The biggest challenge to our current health care system lies in the inability to provide long-term catastrophic insurance. A single major illness can easily wipe out an entire family's savings and destroy their economic future, and that is for a family that has good health care coverage. It does not take long for coverage to be exhausted in the event of serious long-term illnesses that require extensive care. So I agree in principle with the basis for this point in the Obama plan. Where I find myself skeptical is in the cost. Moving a portion of this burden from the corporation (and individual) to the government does make sense on the surface, but before I fully jump on board I want to see more details around the cost. This one could come with a huge price tag.

Prevent insurers from overcharging doctors for their malpractice insurance and invest in proven strategies to reduce preventable medical errors.

No argument here, although caps on malpractice lawsuits have stumbled in Congress anytime they are proposed. There is no doubt that doctors must be protected from the frivolous lawsuit. What is a misconception, however, is the idea that malpractice insurance accounts for a significant portion of our health care costs. It doesn't. In any case, I support the concept behind this point, regardless of its ability to reduce health care costs.

Make employer contributions more fair by requiring large employers that do not offer coverage or make a meaningful contribution to the cost of quality health coverage for their employees to contribute a percentage of payroll toward the costs of their employees health care.

Some states do have laws requiring any employer with 10 or more employees to offer some form of heath insurance. Enforcing this type of requirement is certainly the right approach. The best solution to the health care issue is not socializing the health care system. Rather, the best solution lies in ensuring that anyone that wants a job can find a job, and requiring those employers to provide health care options to their employees.

Establish a National Health Insurance Exchange with a range of private insurance options as well as a new public plan based on benefits available to members of Congress that will allow individuals and small businesses to buy affordable health coverage.

Read this one carefully. I believe the gut reaction of most conservatives will be to scream "socialism" when this point is raised, however if you read it carefully it's nothing of the sort. What Obama is proposing sounds more like a national pooled plan that allows individuals and small businesses to take advantage of the bulk purchasing power already available to large corporations. This concept actually makes a lot of sense, and may be the best solution offered to reduced the cost to individuals or small businesses. It's that loss of bulk buying power that cripples the ability of the individual to obtain affordable health care on their own.

Ensure everyone who needs it will receive a tax credit for their premiums.

As they say, the devil is in the details and this talking point lacks any at all. It's hard to comment on the viability of an option that does not define need, does not define the amount of a tax credit, and fails to account for the funding of that tax credit. This talking point is political campaign fluff, pure and simple.

Lower drug costs by allowing the importation of safe medicines from other developed countries, increasing the use of generic drugs in public programs and taking on drug companies that block cheaper generic medicines from the market

While I'm grateful to see the adjective "developed" used in this context, I oppose the importation of drugs from other countries. The reason, though, may surprise you. A great deal of drug research is done in the United States. We Americans pay a very high premium for that research. Drugs that are imported from other countries are the result of that research, but the cost is not being shared across the board. Rather than allow the importation of cheap drugs - many created as the result of American research - we should require the cost of that research to be passed on to the drugs we export. Our own pharmaceutical companies are not passing that burden on to overseas buyers, so we end up paying an artificially high cost. That's the part that must be corrected, and importing drugs is not the answer.

Require hospitals to collect and report health care cost and quality data.

This is just sound business practice. If hospitals aren't doing that today, then the first question should be "why aren't they?"

Reduce the costs of catastrophic illnesses for employers and their employees.

This sounds great, but without details it's just political campaign fluff. Cost reduction is not something you can mandate, so let's see some details on how it will happen.

Reform the insurance market to increase competition by taking on anti-competitive activity that drives up prices without improving quality of care.

This is another point that sounds very good, but is sorely lacking in details. Before signing up for this one, I'd like to see how the Senator plans to reform the insurance market. Without those details, this one also falls into the campaign fluff category

So now comes the multi-billion dollar question. How will the Obama plan pay for itself? Straight off the website he says:

"Barack Obama will pay for his $50 - $65 billion health care reform effort by rolling back the Bush tax cuts for Americans earning more than $250,000 per year and retaining the estate tax at its 2009 level."

What will pay for it is a tax increase for those making more that $250,000 per year. Now, the question you have to ask yourself is this. What impact will be felt by the lower and middle classes if we increase the tax burden on the wealthiest Americans? In my view, a tax increase at the high end will result in more American jobs being shipped to India and China, lower wage increases (that already trail inflation by 50%), more layoffs, and higher prices for goods and services. Increasing taxes on corporations and the folks that run them is not the solution.

In summary, there are some very solid points in the Barack Obama plan. Overall, I think the plan is a good starting point for discussion. I do not like the method of paying for it, preferring instead that we reduce other areas of the budget to compensate for this increase. On the whole, however, in comparing this plan with the one offered by Senator McCain, I believe the Obama plan will increase the number of people currently insured. I don't believe it will reduce cost - in fact, I believe it will increase cost - but in the long run some form of insurance will reach more Americans.

Saturday, September 27, 2008

Election 2008 - Health Care Issue - McCain Version

Over the course of the next week, we'll attempt to examine each of the major issues facing the two Presidential Candidates. Major topics will include Health Care, Foreign Policy, Taxes, and Energy Policy. The first topic we'll examine is Health Care.

Not unexpectedly, both Senator McCain and Senator Obama offer strikingly different options for health care as part of their 2008 campaign platforms. While nobody on either side of the aisle would dispute that something must be done about the health care situation in the US, finding a viable solution that does not compound the existing problems appears quite elusive. In this first of two articles, I'll review the John McCain Plan and will follow with the Barak Obama plan in a second article.

The John McCain Plan


Details of this plan are found on the official John McCain Campaign website.

Currently, most people employed full time by companies with 10 or more employees enjoy some form of health care as part of their employment benefits. Most of those plans include a pre-tax contribution by the employee and a contribution (on average up to 5 times what the employee pays) by the company. That contribution is not considered income and is therefore not a tax burden imparted to the employee.

The heart of the John McCain plan would change that. Under his proposal, the employee contribution would be made after taxes are deducted, and the employer's portion would be taxable income assigned to the employee. On average, the cost of health care in the US is approximately $12,000 for a family of 4 or $4,400 for an individual. (National Coalition on Health Care.) So under the McCain plan, employees choosing a family plan would see their gross income increase by $12,000 or an individual would see gross income increase by $4,400.

To offset this, what McCain proposes is a $2500 direct refundable tax credit for individuals and $5000 for married couples. He envisions a plan whereby the individual would be able to choose their own health provider, either using the one sponsored by the company or choosing one on their own, with the tax credit being paid directly to the provider. Any surplus in the credit would be deposited into a Health Savings Account.

What this portion of the plan fails to consider is that the only viable option for the employee is the plan offered by the employer. An individual simply cannot obtain the same level of coverage at the same price by purchasing a plan on their own. The corporation has the advantage of purchasing a large pooled plan and invariably receives a better rate than any individual could obtain on their own. To purchase a non-corporate sponsored plan, an individual is going to end up paying $4,400 or more minus the $2500 credit, or at least $1900 out of pocket. That is compared to a national average today of about $880.

It's even worse for the family of four. As stated above, the average cost is $12,000 of which the individual typically pays 20%. So today, the individual has a pre-tax expense of about $2400. Under the McCain plan, that individual (purchasing a plan on their own) would end up paying $7000 and would lose the pre-tax benefits of the current system. That doesn't sound like much of a bargain to me.

Sticking with the employer sponsored plans, the employee may come out slightly ahead based on their tax bracket. For instance, for a family of four in the 15% tax bracket, there would be a potential savings of about $800. The individual may see a savings of about $900. Keep in mind, however, that the surplus goes into a Health Savings Plan, so you only really get to use that surplus if you have a major medical issue in that calendar year. It's a "use it or lose it" savings plan, so it does not add to the discretionary income of the individual or family.

What the McCain plan assumes is that there will be greater competition between the health care providers, thus lowering the costs of health care in general. Unfortunately, the assumption is fundamentally flawed. The deck is already stacked in favor of the corporate sponsored plan, so the individually purchased plans will be minimal at best. What is driving the cost right now is the overall cost of prescription drugs, routine tests, and hospital visits. Competition - or lack of competition - on the part of the providers is not a factor, so attempting to increase that competition will have no positive impact.

In point of fact, the competition between providers already exists today at the corporate level. Each year, corporations review their health care options and attempt to negotiate the lowest cost from a variety of providers. Despite that, we still see significant yearly increases in the cost of health care. This year alone, the rising cost was approximately double the current rate of inflation. So clearly, the driving force is something other than competition between providers.

The second portion of the McCain plan is to attempt to cover, at the state level, those individuals that are unable to obtain insurance. This portion of the plan calls for the federal government to work with states to establish "Guaranteed Access Plans" with "reasonable limits on premiums" and "assistance for Americans below a certain income level."

Not surprisingly, this portion of the plan is a bit vague on the details. The vast majority of people that fall into the the category that would warrant a GAP plan are those with extremely low income levels. Well, at that income level, there is absolutely no discretionary income left after paying just the most basic of bills. All too often, these individuals are floating month to month with at least one bill overdue. For these individuals, no premium is at a "reasonable limit". Given the choice of paying the rent or paying for health care, health care will lose.

It must also be noted that the GAP plans being proposed by Senator McCain are at the state level, not national. This sounds very much like another program mandated by Washington but without any federal funding to back it up. Placing that burden on the states all but insures higher state or local taxes, especially in states with depressed economies or low income levels.

What it all boils down to is my belief that the plan as proposed is neither viable nor beneficial to the average American. I believe this plan will do nothing to reduce the cost of health care, will increase the tax burden on the individual at the state level, and will result in even less people covered by some form of health insurance. I can't support this plan as written.

Sunday, September 21, 2008

Financial Bailout Legislation

Perhaps it is time to be reminded of the lyrics of a popular Buffalo Springfield song. "It's time we stop, hey what's that sound, everybody look what's goin down." As to what's "goin down", I'm not referring to the stock market.

Here is a link to the legislation being reviewed in Congress for a $700 Billion bailout in the current credit crisis: (Wall Street Journal: Financial Bailout Package.)

I first want to draw your attention to Section 8 which reads, "Decisions by the Secretary pursuant to the authority of this Act are non-reviewable and committed to agency discretion, and may not be reviewed by any court of law or any administrative agency."

So the Secretary of the Treasury is not accountable either to the courts or to any other administrative agency in the handling of $700 Billion. Am I the only one that has a problem with this? So, what limits do we place on him in the legislation, then? Clearly, Congress must have some protection built in for the taxpayer, right?

Well, then, let's take a look at Section 7: "For the purpose of the authorities granted in this Act, and for the costs of administering those authorities, the Secretary may use the proceeds of the sale of any securities issued under chapter 31 of title 31, United States Code, and the purposes for which securities may be issued under chapter 31 of title 31, United States Code, are extended to include actions authorized by this Act, including the payment of administrative expenses. Any funds expended for actions authorized by this Act, including the payment of administrative expenses, shall be deemed appropriated at the time of such expenditure."

Wait a second, what was that last sentence again? "Any funds expended for actions authorized by this Act, including the payment of administrative expenses, shall be deemed appropriated at the time of such expenditure."

Am I just too cynical in my old age, or does that pretty much grant the Secretary Carte Blanche in using the proceeds from the sale of any of these securities for such administrative expenses as oh, say, salaries or any other perk you can imagine without court or other agency review? I'd say the Treasury Department just struck the mother lode on this one.

For the record, I totally oppose any bailout package that does not contain the following:
  • Clear, well-defined oversight by one or more agencies external to the Treasury Department.
  • Clear, well-defined criteria regarding the situations in which any federal funds may be used.
  • Provisions stating that the sales of any securities purchased by these funds must be used to off-set the establishment of the fund. In other words, the funds must be used to pay back the tax payer.
  • A clear set of restrictions placed on the Banking, Brokerage, and Insurance industries designed to prevent a future financial melt-down of this magnitude.
That last point is the key. While I've heard endless talk about bailing out corporations on the verge of failure, I've heard no talk at all about preventing this from ever happening again. We must be mindful that those safeguards were in place prior to the mid-1990s, and they must be reinstated. Those safeguards must include:
  • Prohibitions on the combined ownership of banks, insurance companies, and brokerages by the same corporations or holding companies. Each industry must be insulated from the other.
  • Federal requirements regarding the ability of a borrower to pay back a loan. Clearly, leaving it up to the banks as we've been doing for just over a decade is not working. The elimination of federal requirements resulted in a surge in the price of housing as well as a surge in foreclosures and other credit defaults. The requirements must be tightened again, they must be imposed at the federal level, and they must be strict.
  • Restrictions against interstate ownership of banks and holding companies. We must return to the pre-1990s restrictions against banks operating across state or regional lines. This means that a break-up of the largest banks in the nation is an absolute requirement. It was the elimination of this restriction that allowed this current crisis to be global in nature as opposed to being restricted to small pockets of the nation. Just as the government required the break-up of Standard Oil and AT&T, so too must we require the breakup of the large interstate financial institutions.
It is not enough that we simply bailout the companies that are currently drowning. Tossing them a lifeline is one thing. Before reeling in that lifeline, though, we must first implement the measures that will prevent them from ever getting out of control again. In the meantime, scrutinize very closely what is being proposed and what is being done on the federal level to bail these corporations out.

"It's time we stop, hey what's that sound, everybody look what's goin down."